How to calculate net worth without counting the same money twice
Calculate net worth with a worked balance sheet. Learn how to count your home, mortgage, retirement accounts, and credit cards without double-counting.
Dan Faber
June 18, 2026·5 min read·Finance, Net Worth
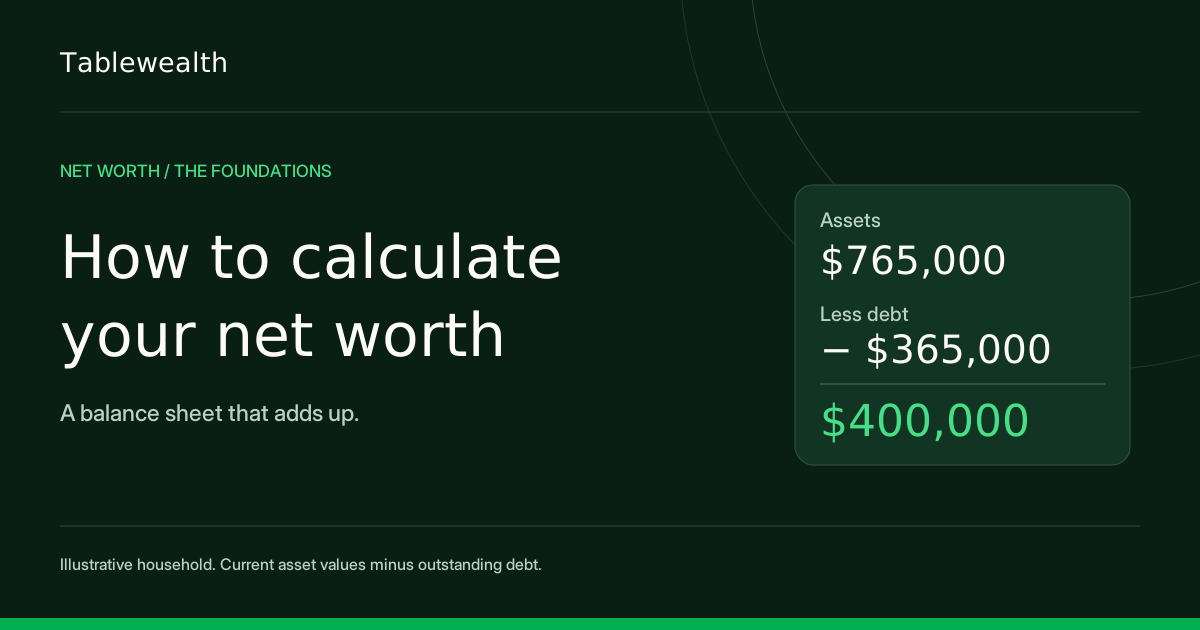
Net worth is the current value of what you own minus what you owe: total assets minus total liabilities. To calculate it, list both on the same date, add each side, and subtract the debt total from the asset total. Salary is income, not an asset you can add to the balance sheet.
That is the definition used in FINRA’s guide to financial foundations. The arithmetic is simple. The useful work is deciding which balances belong in the calculation and making sure each asset and debt appears exactly once.
A net worth calculation with a home, investments, and debt
| Balance sheet item | Asset value | Debt owed |
|---|---|---|
| Checking and savings | $25,000 | — |
| Taxable brokerage, including its cash | $80,000 | — |
| Vested retirement account balances | $145,000 | — |
| Home at estimated current value | $500,000 | — |
| Car at estimated resale value | $15,000 | — |
| Mortgage balance | — | $340,000 |
| Student loan balance | — | $20,000 |
| Credit card balance | — | $5,000 |
| Total | $765,000 | $365,000 |
What should you include in net worth?
Use current account balances for cash and investments. For a home, vehicle, or private investment, use a reasonable current value and record the valuation date and method. A purchase price from several years ago may no longer describe what you own today.
Set the ownership boundary first. A household statement can include both partners’ accounts and debts; an individual statement needs a consistent treatment of shared ownership and legal debt obligations. Count a joint account once in the household total. Do not halve a loan solely because two people use the asset if your actual liability is different.
- Include checking, savings, investment accounts, and vested retirement balances.
- Include real estate and other significant property at supportable current values. If you omit small personal possessions, keep that convention consistent.
- Subtract mortgage, student, auto, personal, and margin loan balances, plus credit card debt and other amounts already owed.
- Keep expected salary, hoped-for inheritances, and unvested equity outside the current asset total.
- Note estimated values separately from account balances so the total does not imply more precision than the inputs provide.
Does your house count? Yes, with the mortgage accounted for once
In the example, the home contributes $500,000 of assets and $340,000 of debt, for $160,000 of equity. You can represent that property using its gross value and a separate mortgage, or use a single net equity figure. The gross-value method makes the debt easier to inspect.
A sale-proceeds estimate answers a different question. It can subtract selling costs and applicable taxes from equity, but label that adjustment explicitly. A standard balance sheet value and the cash you would receive after selling a home need not match.
Count retirement accounts and brokerage holdings at the right level
Retirement accounts belong in total net worth even when the money is intended for later life. Use vested balances for this worksheet and keep a separate note for tax treatment. A dollar in a traditional retirement account and a dollar of bank cash need not provide the same after-tax spending power.
For IRA tax and early-distribution rules, see the IRS IRA overview. Keep any after-tax planning estimate separate from the account-value total.
Use either the investment account balance or a reconciled sum of its holdings and cash. If an $80,000 brokerage account consists of $75,000 in funds and $5,000 in cash, adding all three figures would incorrectly report $160,000. Holdings explain the account balance; they are not extra assets on top of it.
Moving money and paying principal do not create an instant gain
A transfer from savings to a brokerage account changes where money sits, not total net worth. Likewise, using existing cash to repay loan principal reduces an asset and a liability by the same amount. Avoid reading either transaction as a new investment return.
Include a credit card balance even if you pay it in full every month. The debt exists on the snapshot date. Omitting it while counting the cash reserved to pay it makes the household look wealthier than it is.
Turn the calculation into a monthly check you can trust
Save one dated snapshot each month using the same ownership and valuation rules. When the total jumps, check for newly added accounts, missing debt, stale property values, and duplicate imports before calling the change investment performance. Negative net worth simply means the included debts exceed the included assets; the direction and causes of change still matter.
The net worth spreadsheet guide shows how to organize a repeatable worksheet. Keep columns for balance date, source, ownership, and whether a value is estimated.
In Tablewealth, review account inclusion and manual valuations using the investments and net worth checklist. Once the balance sheet reconciles, save it as your starting point for the next monthly review.
Related calculators